
Cross-Border Equipment Leasing: Global Supply Chain Strategies
or complex compliance issues.
clearance and fund security.
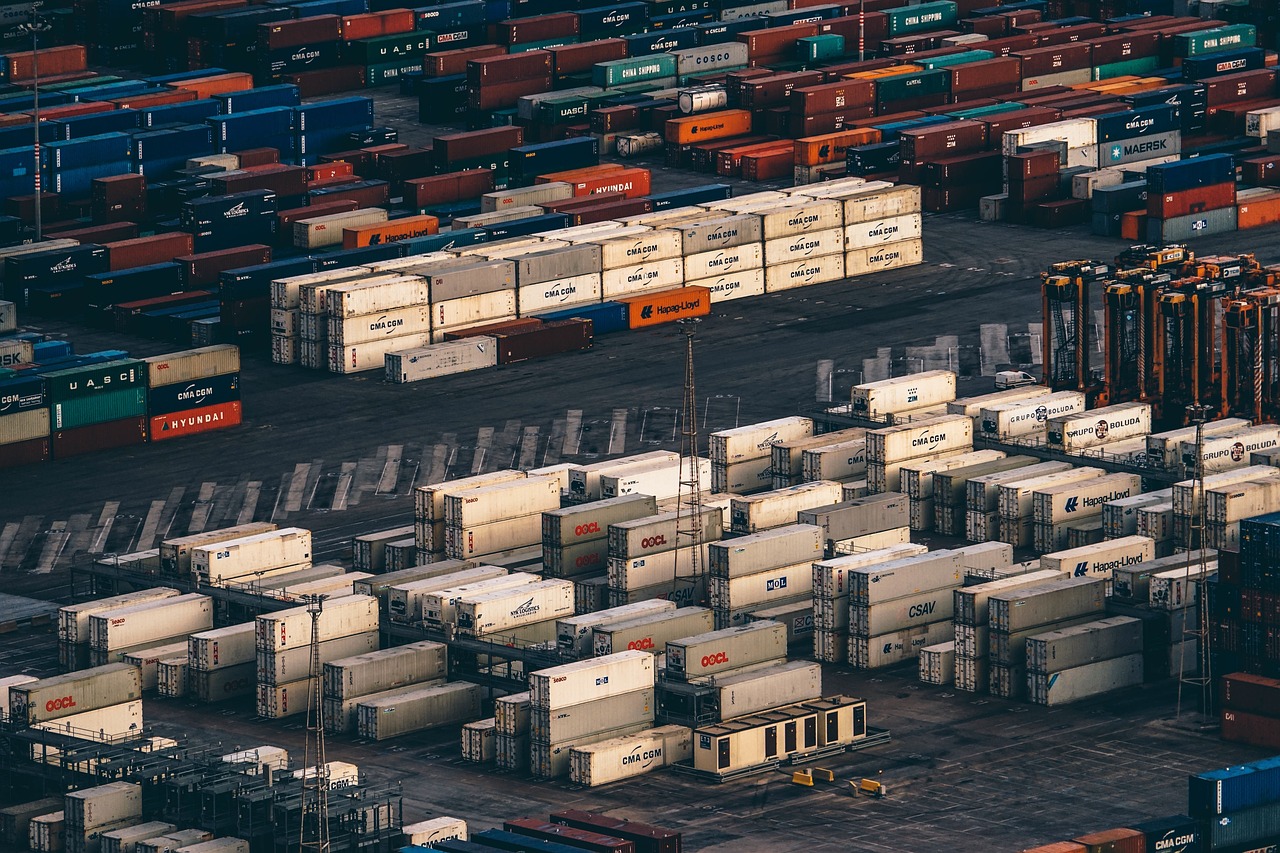
The Cross - border Breakthrough Path of Equipment Financial Leasing
Under the backdrop of the global industrial chain reconstruction in 2025,it has become an important means for manufacturing enterprises to alleviate financial pressure by introducing high-end equipment through financial leasing.According to the latest statistics from the General Administration of Customs,the import of precision processing equipment by financial leasing increased by 37% year-on-year,indicating a strong market demand for structured financial solutions.
Comparison of Three Mainstream Operation Modes
The following operation forms mainly exist in the equipment financial leasing in agency services:
- DirectLeasingMode
- Theagencycompanypurchasestheequipmentandthensubleasesittotheend-user.
- Theownershipoftheequipmentbelongstotheleasingcompany.
- Suitableforshort-termequipmentneedswithin5years.
- Sale and Leaseback Mode
- Theenterprisesellsitsownequipmenttotheleasingcompanyandthenleasesitback.
- Itcanreleasethevalueofexistingequipmentassets.
- Thecapitalreturncycleisshortenedby40-60%.
- Cross - border Sub - leasing Mode
- Completemulti-layerleasingthroughtheoffshoreSPVstructure.
- Effectivelyavoidtheriskofexchangeratefluctuations.
- Thecomprehensivefinancingcostisreducedby15-20%.
Comparative Analysis of Capital Occupancy (Unit: 10,000 yuan)
- TraditionalProcurement:Theequipmentpaymentof5millionyuanneedstobepaidinfull.
- FinancialLeasing:Only20%oftheequipmentvalue,thatis,1millionyuan,needstobepaidintheinitialstage.
- Thecash-flowdifferenceina5-yearperiodreaches4millionyuan.
Key Points of Tax Planning in 2025
Regarding the updated content of Announcement No.58 of the General Administration of Customs,it is recommended to pay special attention to:
- Equipmentwithaleasetermofmorethan3yearscanapplyforinstallmentpaymentofcustomsduties.
- Thefinancingleasecontractneedstoclarifytheinterestcalculationmethod.
- Forcross-bordersub-lease,theregistrationcertificateoftheoverseasSPVcompanyneedstobesubmitted.
- Thespecificvaluationmethodforresidualvaluedisposalneedstobestipulatedinthecontract.
Four - fold guarantee mechanism for risk prevention and control
- ExchangeRateLock-inClause:Stipulateanexchangeratefluctuationrangenotexceeding1/3oftheleaseterm.
- Equipmentinsurancebundling:Includepropertyinsuranceintheleasepackage.
- Designofexitmechanism:Setarepurchaseclausenotlessthan30%ofthenetvalueoftheequipment.
- Reviewoflegaltexts:Itneedstoincludedetailedrulesforhandlingforcemajeure.
Three - dimensional evaluation system for service provider selection
- Capabilityofcapitalchannels:Therearenolessthan3multinationalbanksascooperativefinancialinstitutions.
- Customsclearancerecords:Therearenomajorviolationsinthepastthreeyears.
- Localizedservicenetwork:Therearebranchessetupattheequipmentusagelocation.
A certain auto parts manufacturer successfully introduced German precision machine tools worth 12 million euros through a cross - border sub - lease plan.The project adopted a 3 + 2 lease structure,reducing the capital expenditure in the first year to 2.88 million euros.At the same time,0.76 million euros in tax expenses were saved through the VAT deferral policy.This case verifies the significant advantages of structured financial plans in equipment introduction.
Was this helpful? Give us a like!
Contact our experts for compliance audits, precise quotes, and one-stop customs support.
Recent Comments (0) 0
Leave a Reply